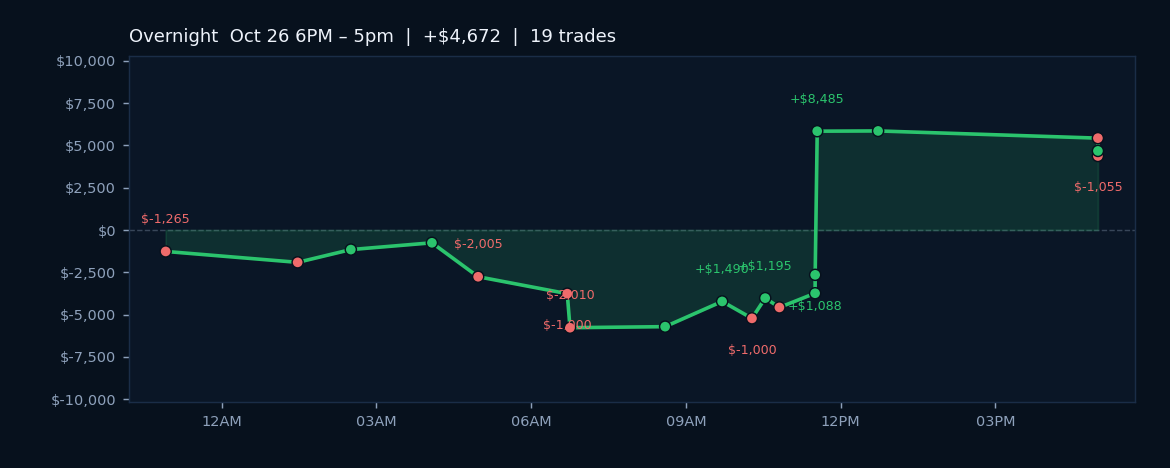
The algos grew by +0.53% on the cumulative total, capturing $4,672.50 in net P&L across 19 trades with a 52.6% win rate (10W / 9L). The session's 1.47 profit factor and balanced gross split of $14,627.50 profit against $9,955.00 loss reflect deliberate entry discipline in an environment the AI Regime confirms is locked in low_vol mode with 100% confidence. Equity futures held resilient: ES stayed pinned between the overnight low of 7699.75 and overnight high of 7749.25, while NQ and MNQ extended overnight pushes toward their session highs, neither breaking decisively above prior-day closes. The average winner of $1,462.75 outpaced the average loser of $1,106.11 by a margin consistent with asymmetric risk management, though the 52.6% win rate underscores the challenge of initiating high-conviction trades in subdued volatility conditions.
Energy data overnight printed mixed signals ahead of tomorrow's FOMC statement and rate decision (forecast holding at 4.00%). API crude fell 2.031M barrels against a forecast of +0.8M, while gasoline stocks swung to a +2.39M build after prior week's draw, suggesting demand softness. The dollar index and bond futures remain key watch points given the Fed's messaging window opening at 2 p.m. ET tomorrow. Concurrent macro data from Chile's central bank flagged persistent weakness lasting longer than expected, and the IMF reached accord on Argentina's third review, neither of which materially shifted overnight futures positioning. Earnings acceleration begins Wednesday with MSFT and GOOGL reports, followed by AMZN on Thursday.
AI sentiment tilts negative with AI Pi at 63.1%, a mild bullish lean that contrasts with the subdued price action. The regime filter's low-vol reading and two active loss-limit recommendations (one flagging a $1,715.00 daily threshold, the other $1,230.00) suggest the system is tightening entry criteria to avoid whipsaws in narrow ranges. Seasonality data for mid-term years from this calendar point shows the next trading week averaged +0.63% with a 68% win rate (19-year sample), a green historical tailwind that may extend into the post-FOMC landscape.
The setup entering Tuesday hinges on Fed communication and the regime filter's stance; low-vol persistence and the seasonal lean favor mean-reversion scalps over trend-following extensions once the statement crosses.